Motilal Oswal Upgrades JSW Cement to Buy Citing Growth and Cost Improvements
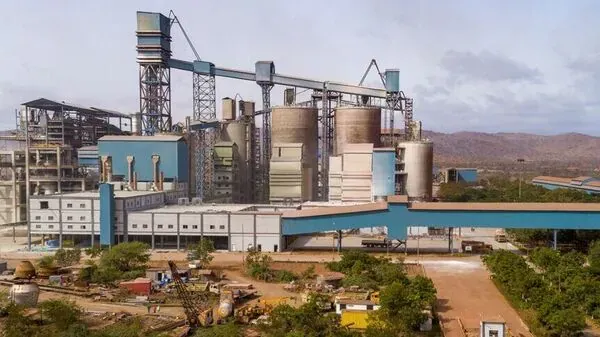
JSW Cement is positioned for medium-term growth driven by strong volume momentum and geographic diversification, notably its new North India plant in Nagaur, Rajasthan. While the company faces near-term cost pressures from higher power, fuel, and operating expenses, cost-efficiency initiatives and plant stabilization are expected to improve margins. Industry volumes grew 10-12% year-on-year in mid-2026, with JSW Cement's overall volume growth reaching 23-25% including the new plant. Motilal Oswal upgraded the stock to Buy with a target price of Rs 146, citing growth potential and improving cost structure.
First-hand measurement across 3 sources
We measured how 3 outlets covered this story. No outlet gave this story a measurable political slant — there is no left–right reading to report. Overall sentiment is positive (68/100). Lens Score 31/100.
Outlets measured: mint, moneycontrol, economictimes. See how each one headlined and framed the same story in the source comparison below.
AI Analysis
Sentiment was consistent across outlets (55–75/100), indicating broadly factual reporting rather than editorialising.
Coverage timeline
economictimes broke this story on 21 Sept, 04:57 am. Other outlets followed.